Skip to content
RiskTemplates · The Daily Brief Thursday, October 22, 2026
Wire DOJ WHIP Whistleblower Rewards Put a 120-Day Clock on Internal Investigations OCT 20
Template Updated September 2026

New Product Risk Assessment Template

Structured risk review process for new products, services, and business initiatives.

Price

$59

One-time. No subscription. Use forever.

Buy & download — $59 →
◆ Secure checkout ◆ Emailed access ◆ Fully editable ◆ 30-day money-back

Delivered immediately after checkout — your template and guide links are emailed to you with your receipt.

Built for risk and compliance teams at financial-services organizations

◆ Quick buying summary

What you get and when you can use it

Good fit if
Your bank partner is asking for a formal risk assessment before approving a new product launch
Format
Editable Excel workbook plus companion PDF guide. Instant download after checkout.
Need the methodology first?
Read the New Product Risk Assessment Template Guide.
Time to value
Start reviewing, editing, and assigning owners the same day; customize to your organization before sharing outputs externally.
After purchase
After payment, download every file immediately from the confirmation page. RiskTemplates also emails a secure access link, and Stripe sends the payment receipt separately. No account required.

◆ What's included

  • ◆ Trigger Screen: six questions that decide full assessment vs. abbreviated review, with the rationale recorded
  • ◆ Risk questionnaire: 77 questions across 12 categories (Compliance, Regulatory, Operational, Technology, Fraud, Third-Party, Credit, Liquidity, Data/Privacy, Reputational, Strategic, Model), including AI features, scams, Nacha fraud monitoring and customer-funds reconciliation
  • ◆ Money and data flow mapping tab for tracing settlement, prefunding and data-sharing risks
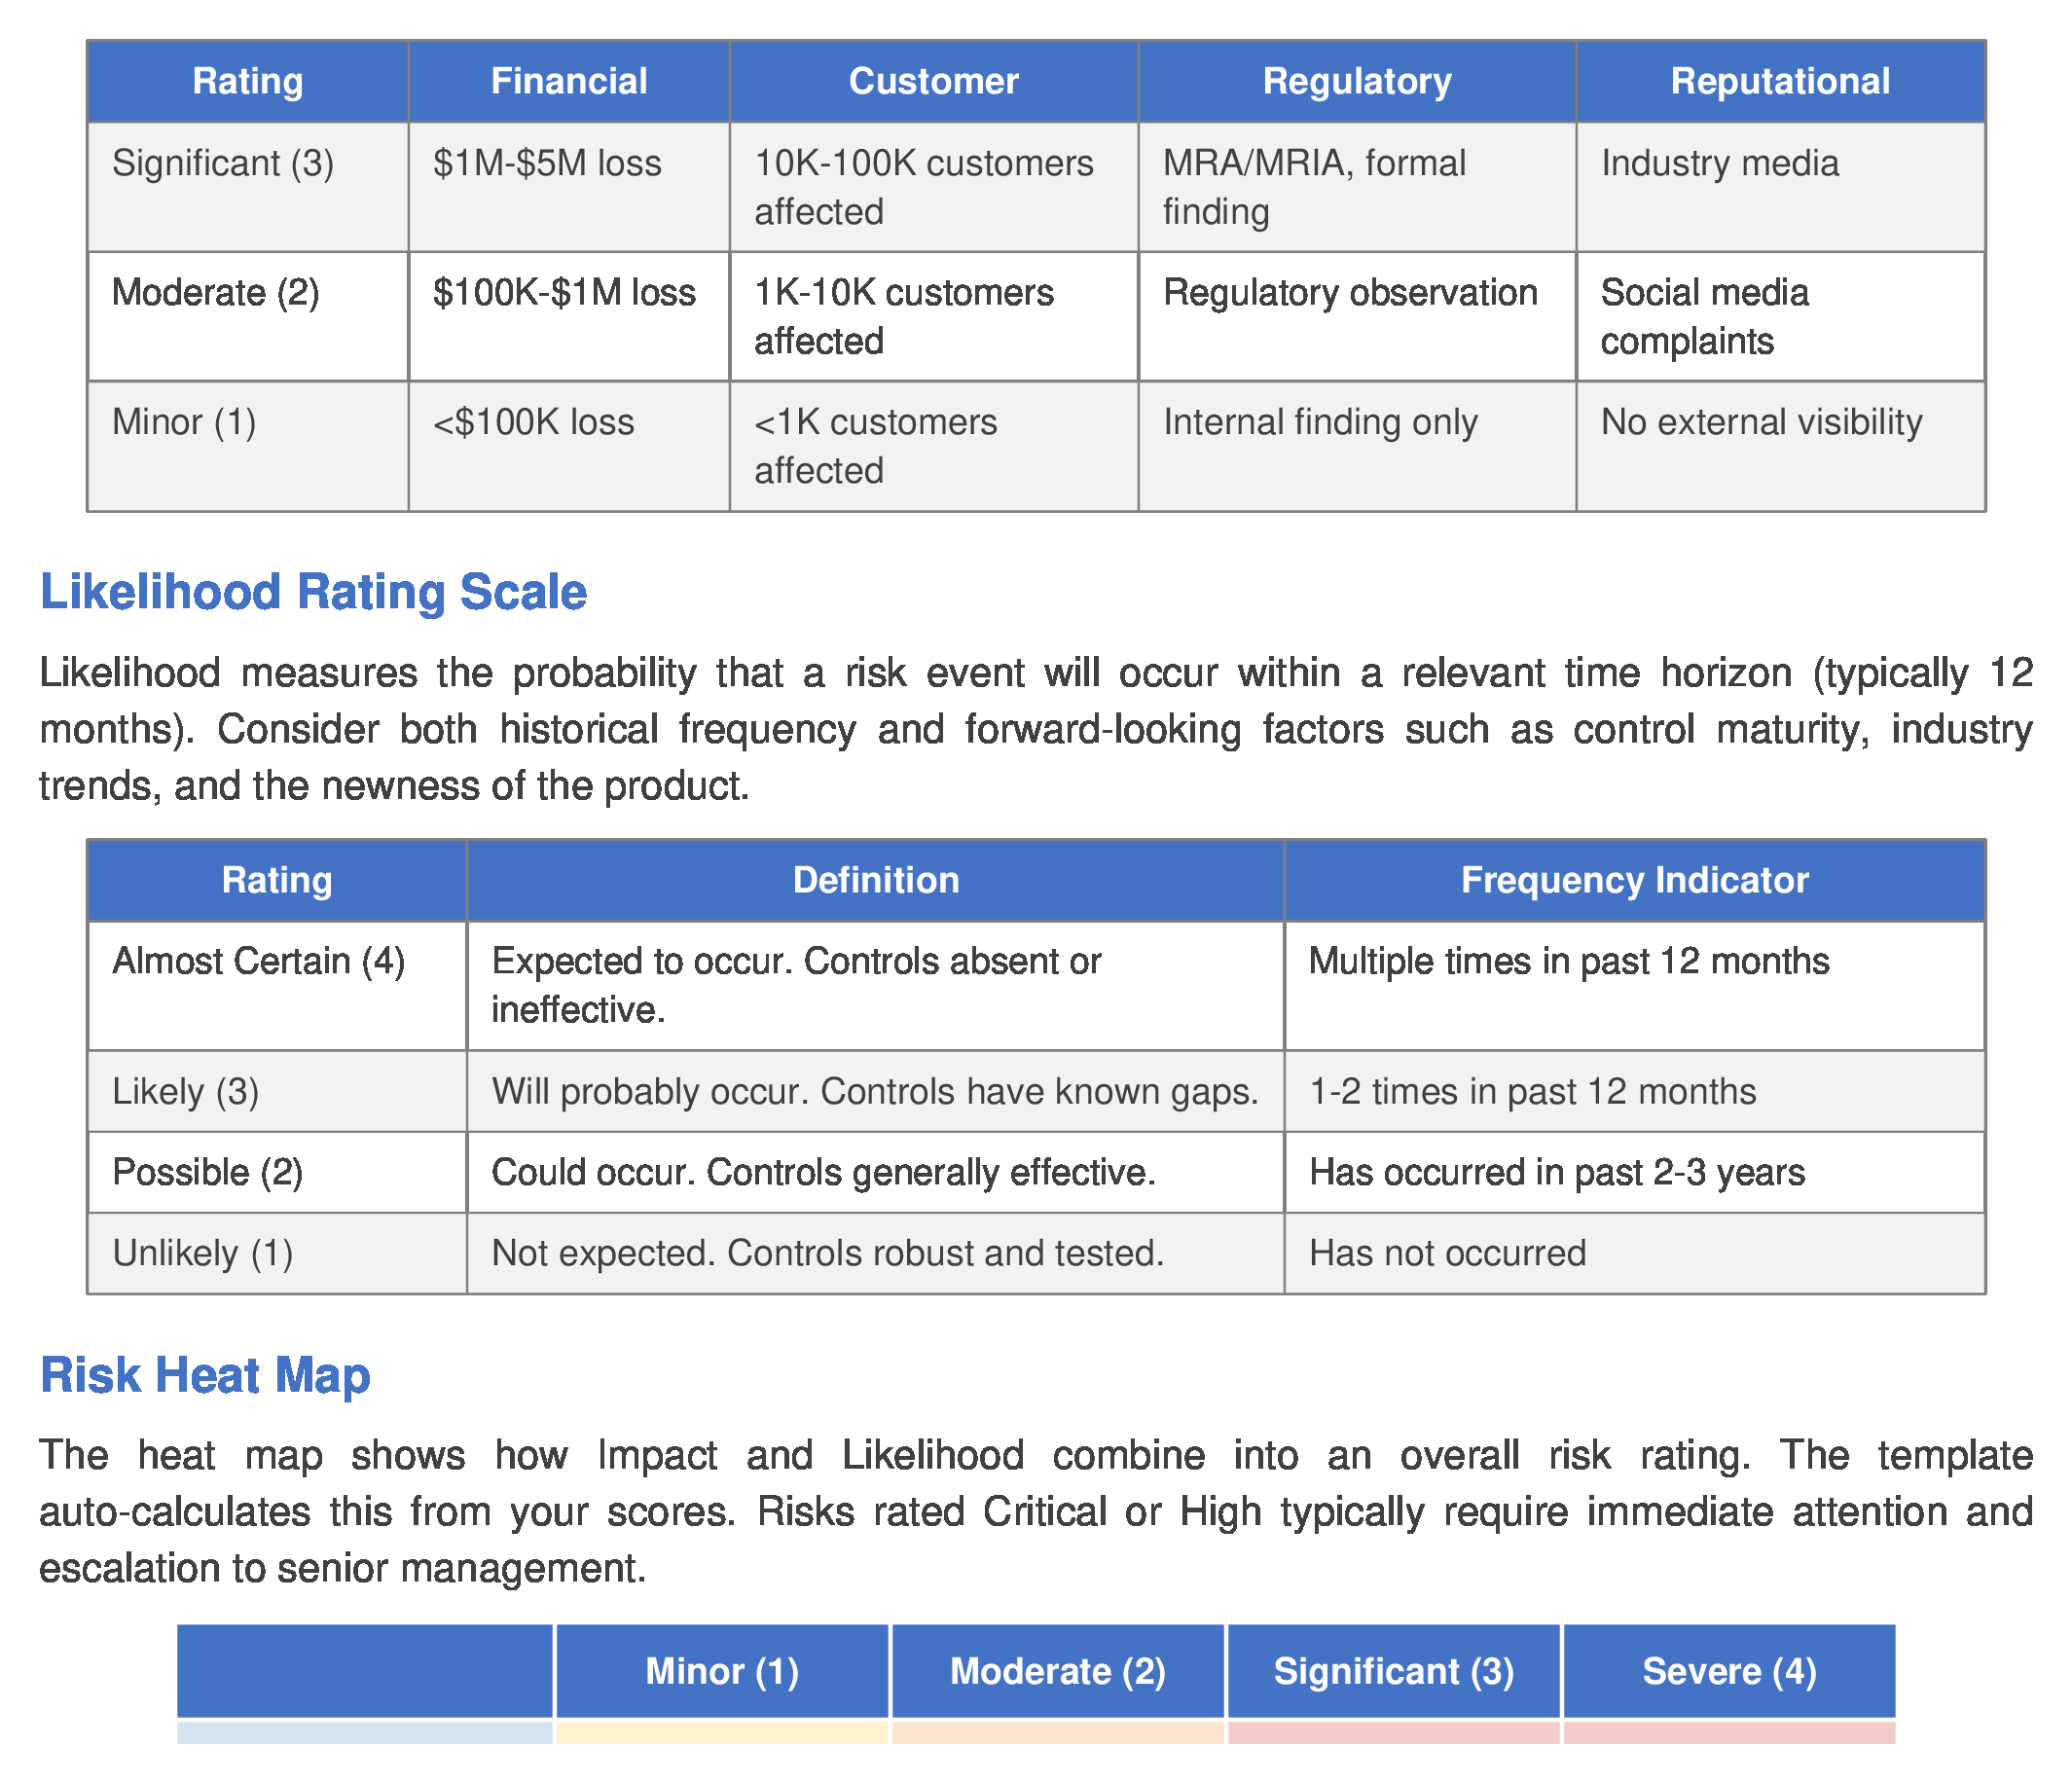
  • ◆ Risk Register with inherent and residual ratings from a 4×4 heat map, treatment decisions, and a Check column that flags scoring and data-entry errors
  • ◆ Pre-Launch Checklist — 64 items across 9 categories with owners, due dates and a launch gate that also requires a reason for every N/A, a completed Trigger Screen, a complete Coverage Matrix and a clean Risk Register
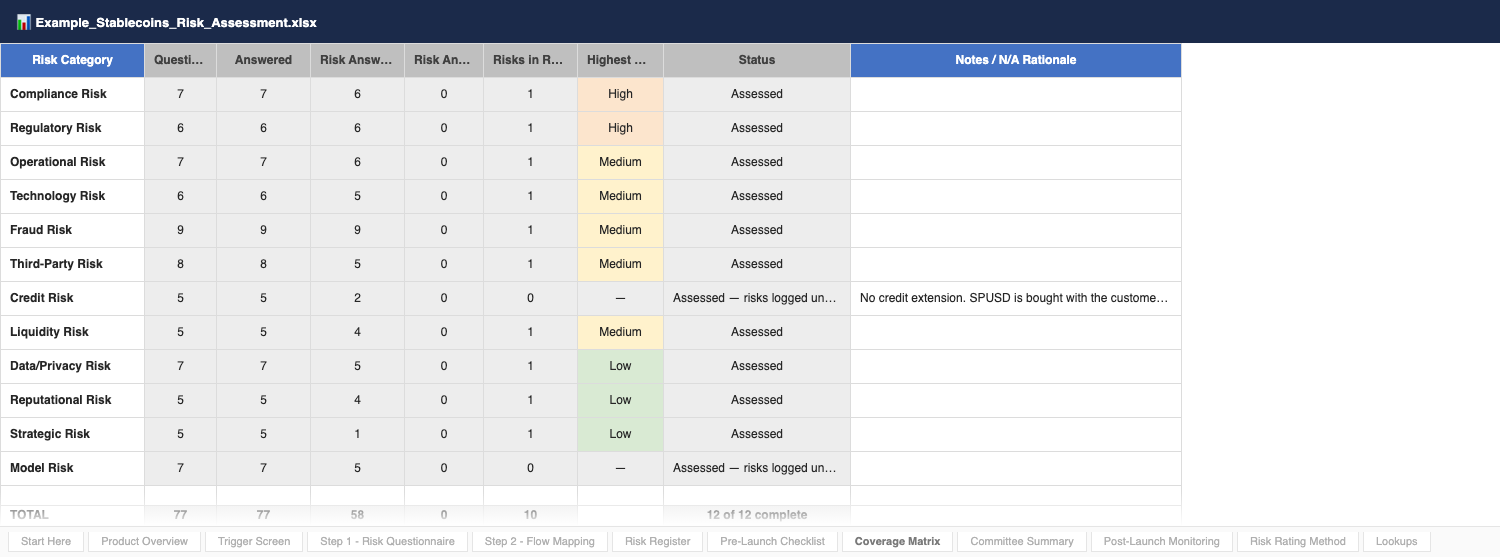
  • ◆ Calculating Coverage Matrix, one-page Committee Summary, and Post-Launch Monitoring with 30/60/90-day reviews
  • ◆ 4 worked examples (BNPL, Instant P2P, Embedded Finance / BaaS, Payment Stablecoin), completed through the committee submission and updated for 2026
  • ◆ 24-page guide: 2026 regulatory expectations, scoring method, committee brief format, and a 30-day rollout with workshop agendas

Use rights: customize for internal business use and use outputs with your auditors, customers, bank partners, and regulators. Do not resell or redistribute the template files.

◆ Preview

See what the template covers.

Trigger Screen — six questions that decide whether a change needs a full new product risk assessment, with the result and rationale

Trigger Screen — six questions that decide whether a change needs a full new product risk assessment, with the result and rationale

Impact scale with financial, customer, regulatory and business thresholds, and the 4×4 impact × likelihood heat map

Impact scale with financial, customer, regulatory and business thresholds, and the 4×4 impact × likelihood heat map

Coverage Matrix — questions answered, risk answers, linked risks and status for all 12 risk categories

Coverage Matrix — questions answered, risk answers, linked risks and status for all 12 risk categories

● Case file

When new product launches make the news for the wrong reasons

These public cases illustrate product, partner, disclosure, suitability, and regulatory-classification risks. They are prompts for review and scenario analysis, not proof that this template would have prevented a particular incident or outcome.

April 2024

Synapse Bankruptcy — Consumers Cut Off From Their Funds

Synapse, the middleware connecting consumer fintech apps to partner banks including Evolve, filed Chapter 11 on April 22, 2024. According to the CFPB, on May 11, 2024 Synapse cut off Evolve's access to its systems and Evolve then froze end-user activity; other partner banks also froze accounts, and the ledgers could not show which customer was owed which dollars.

Why it mattersMiddleware failure is a new-product risk, not just a vendor risk. Before launch, map every party in the customer-funds path, require daily reconciliation of customer balances to the bank, and document what happens if the middleware files for bankruptcy.

October 2023

Voyager Digital — FTC $1.65B Suspended Judgment Over FDIC Claims

Voyager told customers "YOUR USD IS FDIC INSURED" and that funds were "as safe with us as at a bank." FDIC insurance covered only the cash Voyager held at its partner bank, not customers' crypto. When Voyager filed for bankruptcy in July 2022, customers lost more than $1 billion in crypto assets.

Why it mattersMarketing language is a regulatory artifact. The new-product assessment must include legal and marketing review of disclosure accuracy — what the customer hears must match what the product delivers. "FDIC-insured" on the wrong asset is a UDAAP problem before it is an FTC case.

June 2021

Robinhood — $70M FINRA Penalty (Largest Ever Ordered by FINRA)

FINRA found Robinhood gave customers false or misleading information, including about margin and negative balances, approved customers for options trading without adequate due diligence, and failed to supervise technology that suffered outages between 2018 and late 2020. FINRA cited a 20-year-old customer who took his own life in June 2020 after the app displayed a negative cash balance of more than $730,000.

Why it mattersCustomer-protection failures usually start as product, disclosure and support decisions made before launch. The Pre-Launch Checklist forces UDAAP review of what customers see, tested error-resolution procedures and trained support — all signed off before go-live.

If you're reading this trying to make sure your next launch doesn't end up on this list — that's exactly why the new product risk review process exists. Here's what you'd recognize:

◆ Good fit if any of these sound familiar

When teams reach for this template.

You're the first risk and compliance hire at your fintech — and there's a launch on the calendar with no documented review behind it.

The 4 worked examples (BNPL, Instant P2P, Embedded Finance, Stablecoins) give you a starting point you can adapt in days. The six-question Trigger Screen tells you whether a full assessment is needed; the questionnaire, risk register and pre-launch checklist do the rest.

Your CEO wants to launch BNPL, embedded finance, instant payments, or stablecoins next quarter and risk hasn't started the assessment.

Start with the closest of the 4 populated examples, then replace its assumptions, risks, controls, and approvals with product-specific information.

Your last product launch shipped without a documented risk review — and now an examiner is asking why.

You can't retroactively run the assessment, but you can document a consistent process going forward. The Committee Summary, Risk Register and Post-Launch Monitoring tab provide a starting structure.

◆ Why now

Updated for 2026: GENIUS Act, CFPB changes, and bank-fintech guidance

The workbook, examples and guide were updated in September 2026 for the GENIUS Act, the CFPB's 2025 withdrawals and repeals, the Reg B amendments, the model risk guidance that replaced SR 11-7, Nacha's fraud-monitoring rules, and the third-party guidance the agencies proposed in September 2026. Requirements depend on the product and jurisdiction, so confirm current primary sources and obtain legal or compliance review before making launch decisions.

◆ Where this fits

Where this fits in your product launch process

  • ◆ If you have a new product review committee — this gives them a standard submission template, scoring matrix, and worked examples so reviews are consistent and defensible across product types.
  • ◆ If you don't have a new product review committee yet — this is your week-one program. The 4 worked examples show what a complete risk assessment looks like; adapt one for your product and you have a starting point.
  • ◆ If you're working with a bank partner — use the populated assessment, scoring matrix, and post-launch monitoring plan to organize the information requested during due diligence.
  • ◆ If your last launch didn't have a formal new product risk review — use the kit to establish a documented process for future launches, with organization-specific governance and review.

◆ What this isn't

Setting expectations.

  • × Not a replacement for legal review — your counsel still reviews specific contractual, regulatory, and consumer-disclosure language for your product.
  • × Not a software platform — these are Excel + PDF templates, not a SaaS new product workflow tool.
  • × Not a substitute for a Chief Risk Officer or new product review committee chair — this is the toolkit they use, not a substitute for the role.
  • × Not theory — these are operational templates with 4 populated worked examples for product types that draw close regulatory and bank-partner attention.

◆ 30-day rollout plan

How to roll this out for your next launch

This sample 4-week sequence applies the process to a real launch, with suggested workshops, owners, and deliverables. Adjust timing and approvals to the product and organization.

  1. Week 1

    Trigger assessment + scoping workshop

    Run the six-question Trigger Screen on the proposed product. If a full assessment is required, run a 60-minute scoping workshop with product, risk, compliance, legal, and engineering. Output: defined scope, risk types in play, target new product review committee date, owner assignments per risk category.

  2. Week 2

    Populate the multi-risk assessment

    Each category owner completes their section of the 77-question questionnaire, then product, engineering and operations map the money and data flow together. Use the worked example closest to your product (BNPL, Embedded Finance, Instant Payments, Stablecoins) as calibration. Output: completed questionnaire and flow map, and a draft Risk Register with inherent scores.

  3. Week 3

    Controls, residual scoring, checklist + bank partner alignment

    Control owners document controls, risk and compliance challenge them and score residual risk and treatments. Run the 64-item Pre-Launch Checklist across the 9 categories. Identify open items and owners. If you have a bank partner, share the risk assessment and scoring summary at the next due diligence touchpoint and capture their feedback. Output: residual scores and treatments, checklist status, partner-feedback log.

  4. Week 4

    Committee submission + go/no-go decision

    Take the Committee Summary to the new product review committee, brief it, capture the decision (Go / Conditional Go / No-Go / Deferred) and any conditions. Set the post-launch monitoring cadence. Outcome: a documented launch decision, with the evidence behind it, ready for your bank partner, board and examiners to review.

◆ Full playbook in the PDF guide

The complete rollout including workshop agendas, attendee lists, and the decision-meeting brief format is in the PDF guide that comes with the template.

◆ Regulatory alignment

Regulatory references (checked September 2026)

The guide includes references intended to help reviewers trace relevant prompts. Confirm applicability and current primary-source text before relying on them:

  • ◆ OCC Bulletin 2017-43 (new, modified, or expanded bank products and services)
  • ◆ Interagency Guidance on Third-Party Relationships (OCC Bulletin 2023-17) and the proposed replacement (OCC Bulletin 2026-46, Sept. 2026)
  • ◆ Joint Statement on Banks' Arrangements with Third Parties to Deliver Bank Deposit Products and Services (July 25, 2024)
  • ◆ FDIC proposed rule on recordkeeping for custodial accounts (Sept. 2024; proposal stage)
  • ◆ GENIUS Act (enacted July 18, 2025) and OCC proposed implementing rules (Feb. 2026)
  • ◆ OCC Bulletin 2026-13 / SR 26-2 model risk guidance (replaced SR 11-7, April 2026)
  • ◆ Regulation B amendments (effective July 21, 2026); Regulation E; Regulation Z
  • ◆ Nacha fraud-monitoring rules (March and June 2026)

Built for new product review committees, product risk teams, and compliance leads at fintechs, banks, and BaaS sponsors.

Last updated: September 30, 2026

◆ Template guide

New Product Risk Assessment Template Guide

How to run a New Product Risk Assessment: 12-category risk questionnaire, 4x4 impact and likelihood scoring, a 64-item pre-launch checklist, and the sign-off flow your risk committee and bank partner expect before go-live.

Read guide →

◆ FAQ

Frequently asked questions.

What are the 4 worked example assessments included?

Fully completed assessments for BNPL (pay-in-4), instant P2P transfers, embedded finance / BaaS, and a USD payment stablecoin issued under the GENIUS Act. Each has every assessment tab completed through the committee submission (the committee decision and post-launch results are left for you) and a "how we identified the risks" section explaining the reasoning, and each was updated in September 2026 for current rules — for example, the CFPB's 2025 withdrawal of its BNPL interpretive rule and the GENIUS Act's reserve and no-yield requirements.

What triggers the requirement for a full new product risk review?

The Trigger Screen asks six questions: is it new to the company, does it change the types of risk, does it materially increase existing risk, does it need new licenses, bank partner approval or critical vendors, does it change how money moves, and is it just a routine enhancement. A Yes to any of the first five means a full assessment; otherwise an abbreviated review may be enough, with the rationale recorded.

What's in the 64-item pre-launch checklist?

Items across 9 categories: Regulatory & Licensing, BSA/AML & Fraud, Consumer Protection & Compliance, Technology & Security, Data Privacy, Third-Party / Vendor Management, Operational Readiness, Financial & Risk Management, and Governance & Documentation. Each item is Required or Recommended with status, owner, due date and evidence, and the launch gate counts Required items still open.

How does the risk committee submission work?

The Committee Summary tab calculates itself from the workbook: product details, trigger result, unanswered questions, unlinked risk answers, coverage status, register rows needing attention, the pre-launch gate, risks by rating, and the top Critical and High residual risks. The committee records its decision (Go, Conditional Go, No-Go or Deferred) and conditions on the same page. The guide includes a brief format and what the committee should challenge.

Does this cover all the risk types in a single assessment?

It covers the 12 risk categories most new fintech products touch in one workbook — add questions if your product has others, and the Coverage Matrix confirms each category was assessed or explicitly marked N/A with a reason. Every risk answer links to a Risk ID on the Risk Register, which scores inherent and residual risk — and the Check column flags any link that points to a risk that is not there.

Can this be used for partnerships and distribution agreements, not just internal products?

Yes. The questionnaire asks whether contracts allocate liability for losses, errors and compliance failures among you, your bank partner and any program manager or distribution partner, and whether a middleware provider sits in the funds flow. The embedded finance / BaaS example walks through a three-party model end to end.

Can I share completed outputs externally?

Yes. You can use completed outputs with auditors, customers, bank partners, regulators, and internal stakeholders. Customize the template for internal business use — just don't resell or redistribute the source template files.

How do I receive the files?

Checkout is handled through Stripe. After payment, download every file immediately from the confirmation page. RiskTemplates also emails a secure access link, and Stripe sends the payment receipt separately. No account is required.

What if it's not a fit?

Email within 30 days for a full refund, no questions asked. The guarantee is meant to remove purchase risk while you evaluate whether the template fits your use case.
● First-time buyer offer

Get 20% off your first template.

Drop your email and we'll send the code.

◆ Not ready to buy?

Start with the free Risk Register.

141 pre-populated fintech risks across 21 categories. ISO 31000 structure.

Download free Risk Register →

◆ Related templates

Pairs well with.

Template
$69

Third-Party Risk Management (TPRM) Kit

Tier every vendor with one documented rule, run due diligence and AI vendor reviews, find contract gaps against the 2023 Interagency Guidance, and track SOC reports, issues, concentration and exits. Excel workbook, guide, Word policy and offboarding checklist.

Template
$59

AI Risk Assessment Template & Guide

Comprehensive AI model governance and risk assessment templates for financial services teams.

Template
$49

Issues Management Tracker & Template

End-to-end issues tracking and remediation management for risk and compliance teams.

◆ Ready when you are

Get the New Product Risk Assessment.

Start building a defensible risk program today.

Buy & download — $59 →
◆ Secure checkout ◆ Emailed access ◆ Fully editable ◆ 30-day money-back

Immaterial Findings · Newsletter

The brief, in your inbox.

Enforcement of the week, a framework breakdown, and the prompts that are actually worth running. Delivered to your inbox. Free.